 agenziaimmobiliarecostarica
Life insurance
Term and permanent plans with beneficiary guidance so income replacement stays aligned with mortgage and education goals.
agenziaimmobiliarecostarica insurance pairs clear advice with life, health, home, auto, and commercial policies designed around how you actually live and work.
Start with the protection pillar that matters most, then layer endorsements as your needs grow.
Term and permanent plans with beneficiary guidance so income replacement stays aligned with mortgage and education goals.
Individual and group options with network reviews, prescription tier checks, and renewal comparisons before deadlines hit.
Dwelling, contents, and liability limits tuned to reconstruction costs, detached structures, and seasonal weather risks.
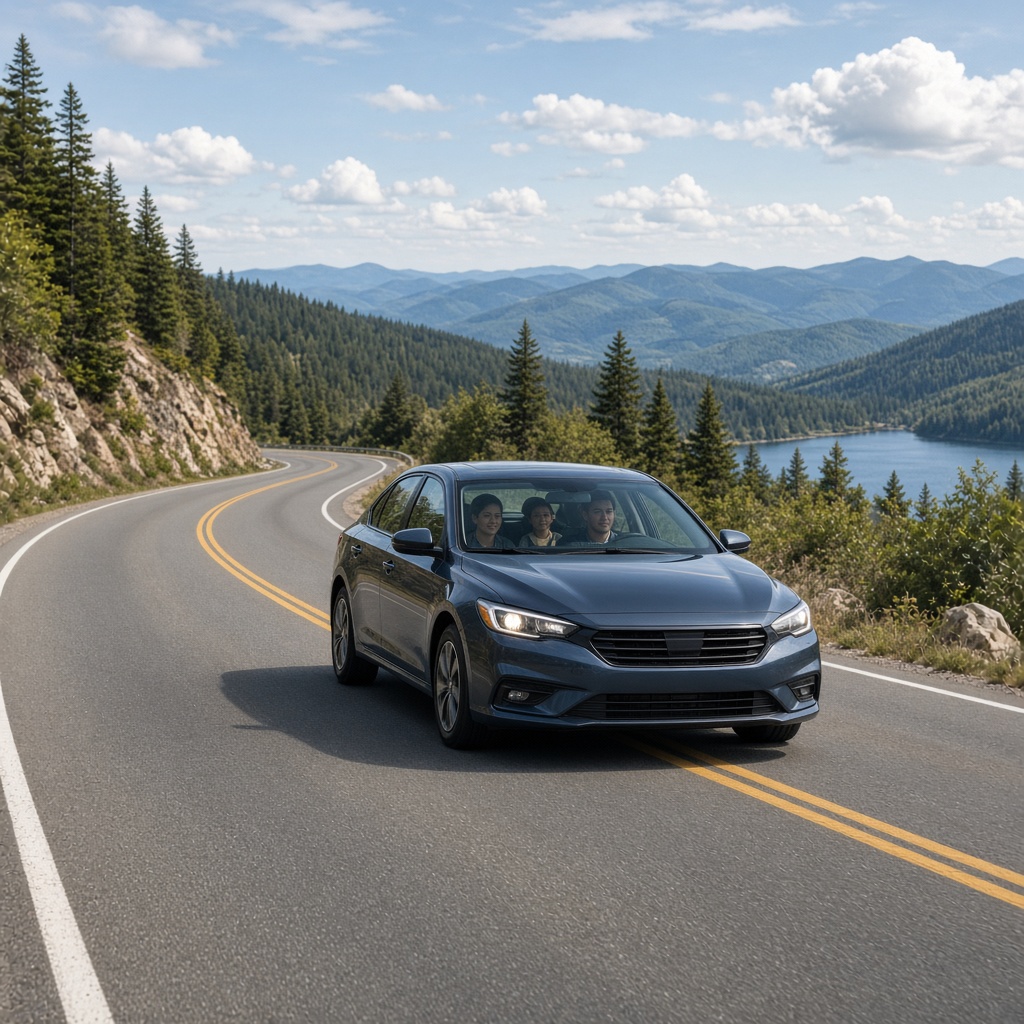
Liability, collision, comprehensive, and uninsured motorist packages for daily drivers, commuters, and multi-car households.
Choosing coverage begins with an honest inventory of what you need to protect, from the people who depend on your income to the buildings and vehicles that keep your work moving. agenziaimmobiliarecostarica insurance advisors walk through each line of risk so you understand deductibles, limits, and exclusions before anything is bound. We compare term and permanent life structures, explain how riders change payouts, and show how beneficiary designations stay aligned with estate plans. When health plans renew, we review networks, prescription tiers, and out-of-pocket maximums so surprise bills do not undermine a household budget. Home policies receive the same scrutiny: replacement cost versus market value, water backup endorsements, and liability extensions for guests or rented equipment.
Auto coverage is more than a card in your wallet. Collision and comprehensive limits should reflect how you use each vehicle, whether you commute daily or keep a classic car for weekends. We clarify uninsured motorist protection, rental reimbursement, and gap coverage when financing is involved. Business owners receive guidance on general liability, professional errors, property schedules for tools, and workers arrangements where applicable. Our process keeps documentation organized so claims teams receive photos, receipts, and police reports without delay. You receive plain-language summaries after every review, not stacks of unexplained forms.
Claims support is where a policy proves its value. We coach clients on first notice of loss, temporary repairs that prevent further damage, and how adjusters evaluate structural versus cosmetic harm. For health claims, we explain prior authorization steps and appeal paths when a network denial feels incorrect. Life insurance beneficiaries learn how to submit certifications and avoid common paperwork errors that slow payouts. We never promise outcomes we cannot control, yet we advocate for complete files and timely follow-up with carriers. Education remains free of jargon wherever possible, because informed clients make steadier decisions when stress is high.
Pricing reflects risk, location, usage, and the limits you select. We illustrate how raising a deductible lowers premium while increasing your share of small losses, and when that trade-off makes sense for your cash flow. Bundling home and auto often unlocks meaningful credits, but only when both policies truly fit; we would rather adjust lines separately than force a bundle that leaves gaps. Business quotes incorporate payroll, revenue bands, and industry codes so liability limits scale with exposure. Every figure on our pricing pages uses a dollar sign so you can compare plans side by side without hidden fees in the footnotes.
Renewals are not automatic approvals. Carriers reevaluate roofs, credit-based insurance scores where permitted, and driver records before sending new premiums. We schedule renewal consults early so you can adjust limits, shop alternatives, or document home upgrades that deserve higher replacement values. For commercial clients, payroll audits and revenue true-ups prevent year-end surprises. Staying proactive keeps coverage aligned with reality instead of with an outdated application from years ago.
Plain-language comparisons for life, health, home, auto, and business lines without hidden exclusions buried in footnotes.
Annual reviews before renewals so limits track renovations, new drivers, equipment purchases, and payroll changes.
Claims coaching from first notice through adjuster visits, including photo lists and receipt organization.
Flexible payment schedules and bundle suggestions only when they genuinely reduce gaps instead of creating them.
Each agent holds active credentials and focuses on a coverage line so you receive depth, not generic scripts.
Life & estate planning
Home & property
Health plan specialist
Auto & fleet
Commercial lines
Claims advocacy
Life quotes estimate income replacement, debt payoff, and education funding needs across term lengths.
Health quotes compare deductibles, copays, and specialist access for your household size.
Home quotes use reconstruction values, roof age, and liability extensions for pools or detached offices.
Auto quotes review mileage, garaging, and uninsured motorist limits for each vehicle.
Business quotes align general liability with payroll, revenue, and equipment schedules.
Gather photos of damage, receipts for emergency repairs, inventory lists for personal property, and any contractor estimates. Your declarations page lists current limits so adjusters can confirm coverage quickly.
Many carriers allow deductible adjustments at renewal or after removing a financed vehicle. We verify whether mid-term changes affect comprehensive or collision rates before you decide.
Review beneficiaries after marriage, divorce, births, or when a business partner exits. Keeping contingent beneficiaries updated prevents delays if primary designations cannot be located.
Most group and individual plans include behavioral health, yet network rules differ. We summarize visit limits, telehealth options, and referral requirements during renewal meetings.
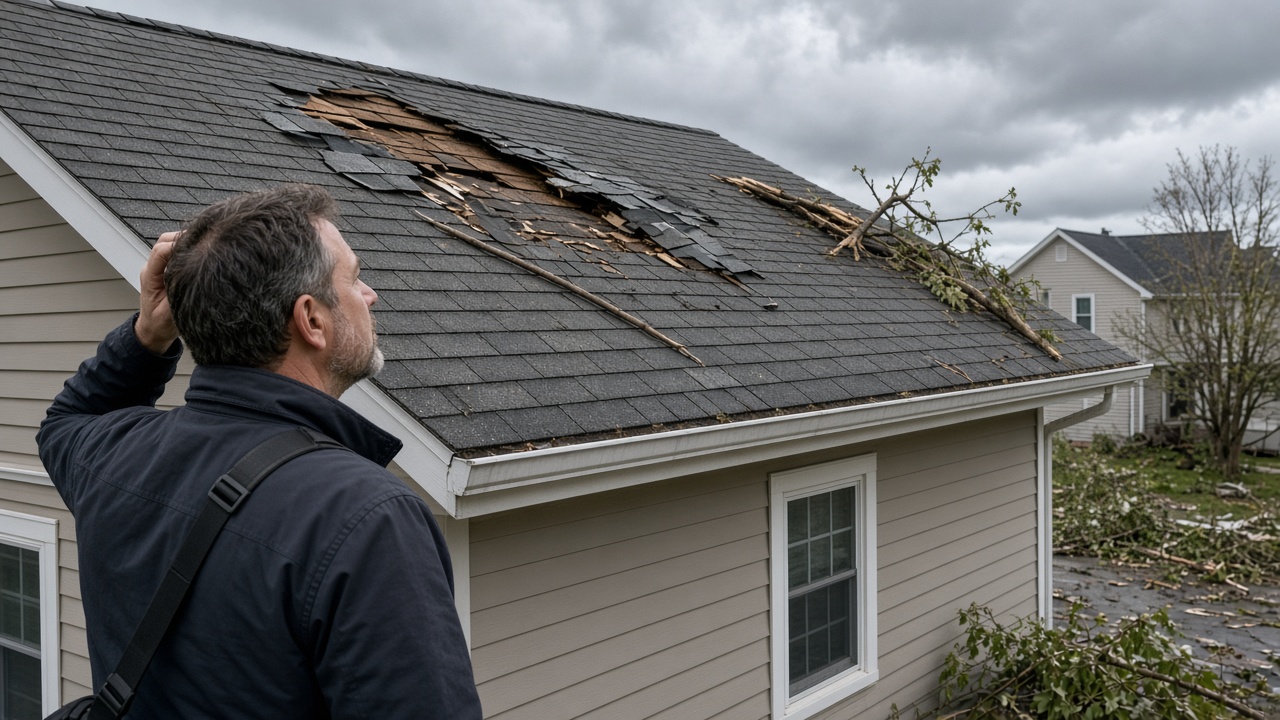
Photograph roofs, drains, and sump systems so adjusters can compare pre-storm condition with new damage.
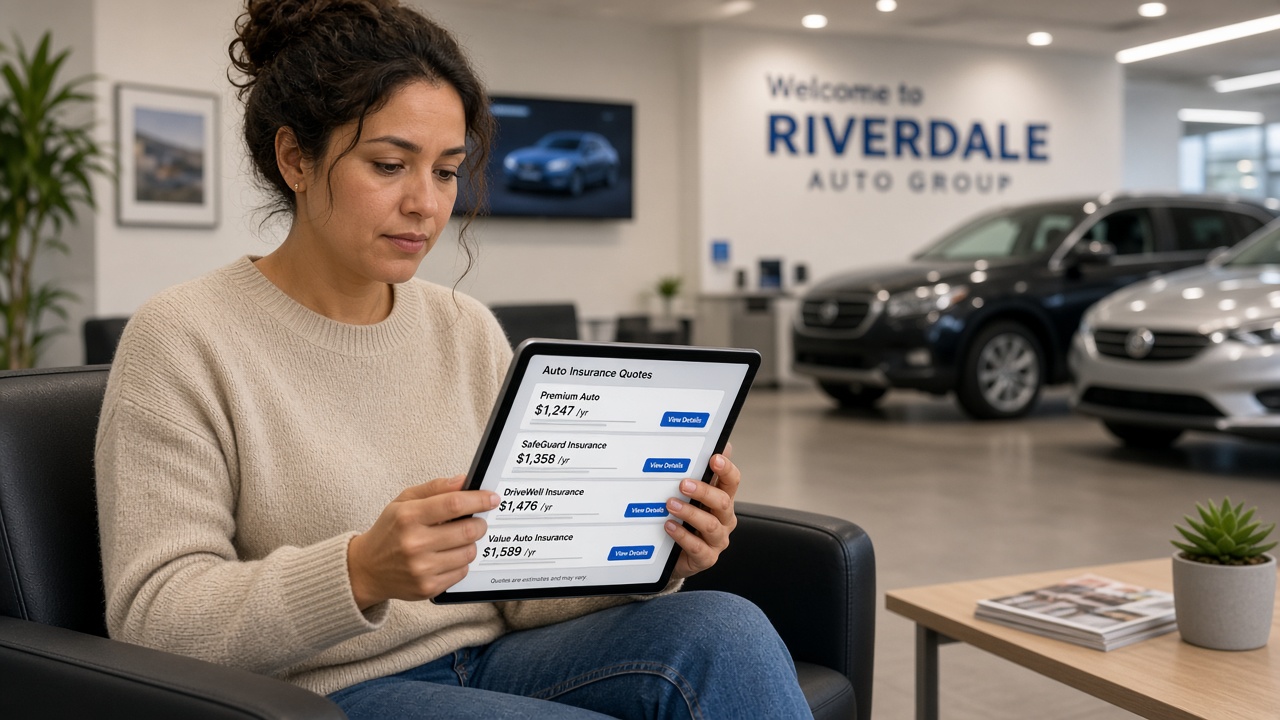
Stacking limits across vehicles can leave gaps; we show how per-accident caps apply when several drivers share a policy.
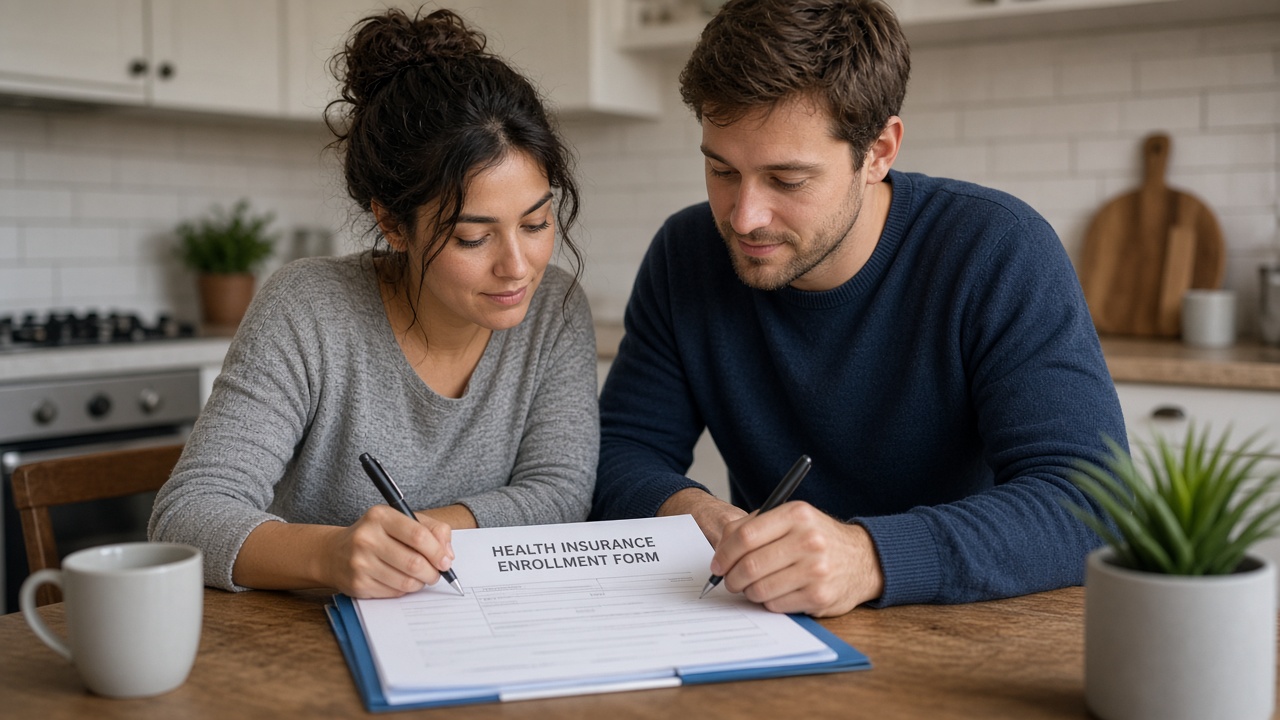
Pediatric networks, prescription tiers, and HSA compatibility should be reviewed before open enrollment closes.
Choosing coverage begins with an honest inventory of what you need to protect, from the people who depend on your income to the buildings and vehicles that keep your work moving. agenziaimmobiliarecostarica insurance advisors walk through each line of risk so you understand deductibles, limits, and exclusions before anything is bound. We compare term and permanent life structures, explain how riders change payouts, and show how beneficiary designations stay aligned with estate plans. When health plans renew, we review networks, prescription tiers, and out-of-pocket maximums so surprise bills do not undermine a household budget. Home policies receive the same scrutiny: replacement cost versus market value, water backup endorsements, and liability extensions for guests or rented equipment.
Auto coverage is more than a card in your wallet. Collision and comprehensive limits should reflect how you use each vehicle, whether you commute daily or keep a classic car for weekends. We clarify uninsured motorist protection, rental reimbursement, and gap coverage when financing is involved. Business owners receive guidance on general liability, professional errors, property schedules for tools, and workers arrangements where applicable. Our process keeps documentation organized so claims teams receive photos, receipts, and police reports without delay. You receive plain-language summaries after every review, not stacks of unexplained forms.
Claims support is where a policy proves its value. We coach clients on first notice of loss, temporary repairs that prevent further damage, and how adjusters evaluate structural versus cosmetic harm. For health claims, we explain prior authorization steps and appeal paths when a network denial feels incorrect. Life insurance beneficiaries learn how to submit certifications and avoid common paperwork errors that slow payouts. We never promise outcomes we cannot control, yet we advocate for complete files and timely follow-up with carriers. Education remains free of jargon wherever possible, because informed clients make steadier decisions when stress is high.
Pricing reflects risk, location, usage, and the limits you select. We illustrate how raising a deductible lowers premium while increasing your share of small losses, and when that trade-off makes sense for your cash flow. Bundling home and auto often unlocks meaningful credits, but only when both policies truly fit; we would rather adjust lines separately than force a bundle that leaves gaps. Business quotes incorporate payroll, revenue bands, and industry codes so liability limits scale with exposure. Every figure on our pricing pages uses a dollar sign so you can compare plans side by side without hidden fees in the footnotes.
Renewals are not automatic approvals. Carriers reevaluate roofs, credit-based insurance scores where permitted, and driver records before sending new premiums. We schedule renewal consults early so you can adjust limits, shop alternatives, or document home upgrades that deserve higher replacement values. For commercial clients, payroll audits and revenue true-ups prevent year-end surprises. Staying proactive keeps coverage aligned with reality instead of with an outdated application from years ago.